How Working Capital Markup is Computed in Pakistani Banking
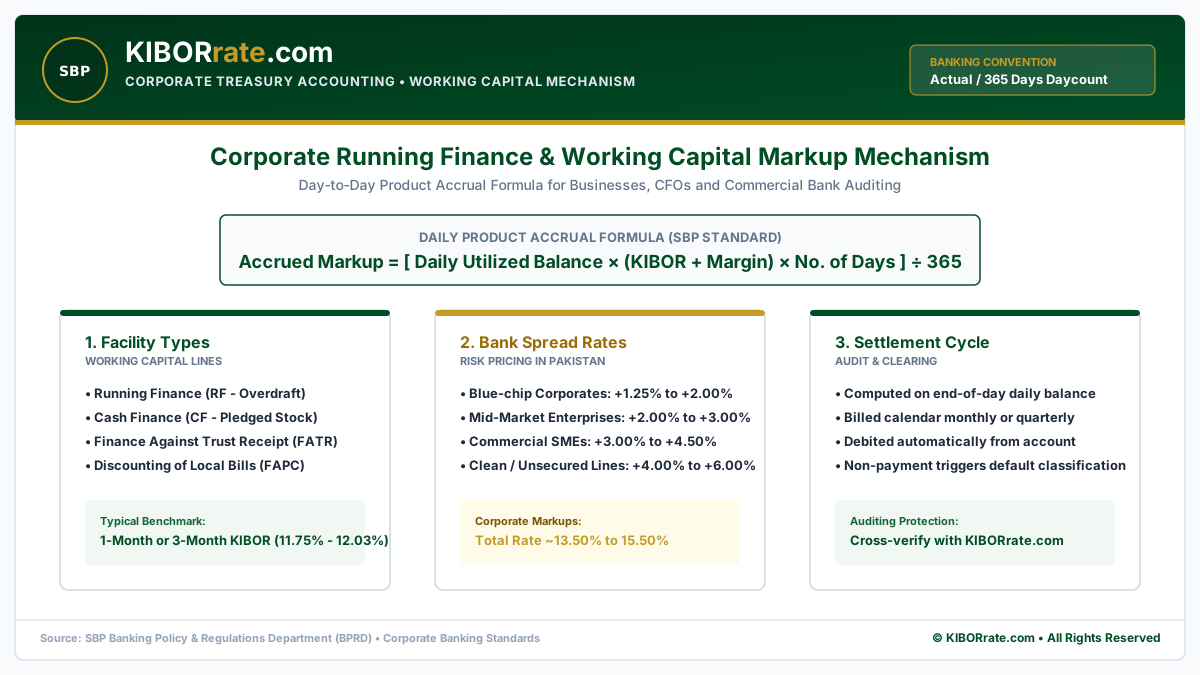
In Pakistan's commercial and industrial sectors, businesses utilize **Running Finance (RF)**, **Cash Finance (CF)**, or **Finance Against Trust Receipts (FATR)** to fund daily inventories, receivables, and operational expenses. Markup on these facilities is charged on a daily product basis.
The SBP Day-Count Convention
Commercial banks in Pakistan apply the Actual / 365 days formula for computing interest on PKR facilities:
Quarterly / Monthly Settlement
Banks calculate accrued interest daily on your end-of-day overdraft balance and debit your current account at the end of every calendar month or quarter.
Audit Cross-Verification
Accountants and auditors use this calculator to verify bank markup advice notices and ensure the financial institution has applied the exact agreed KIBOR spread without discrepancies.
Corporate Lending Guidelines: Running Finance (RF) vs. Cash Finance (CF)
Under the statutory guidelines of the SBP Banking Policy and Regulations Department (BPRD), working capital financing represents the lifeblood of Pakistani trade, commerce, and manufacturing:
Running Finance (RF)
An overdraft credit facility linked directly to a company's business current account. The borrower only pays markup on the exact amount withdrawn and utilized each night, with no penalty on unused balances.
Cash Finance (CF)
Short-term working credit backed by the physical pledge or hypothecation of manufactured inventory, cotton, wheat, sugar, or imported raw materials stored in bank-approved godowns under bank muccadam surveillance.
FATR / FAPC Import Lines
Finance Against Trust Receipts (FATR) bridges foreign Letter of Credit (LC) retirements, allowing industrialists to release raw materials from Karachi port before selling finished goods to downstream wholesalers.
Typical Bank Margins Across Corporate Credit Tiers in Pakistan
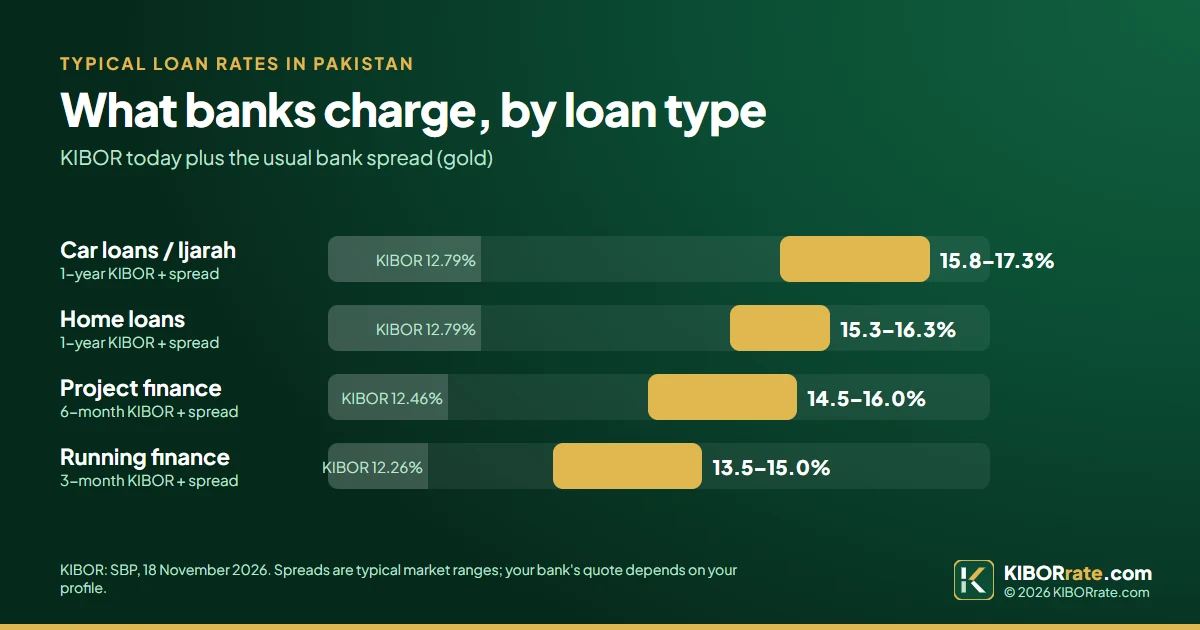
| Corporate / SME Segment | Primary Benchmark | Approved Spread (Margin) | Effective Annual Yield | Facility Collateral Requirements |
|---|---|---|---|---|
| Tier-1 Blue Chip (KSE-100 Listed) | 1-Month or 3-Month KIBOR | +1.00% to +1.75% | 12.75% - 13.78% | Clean / Negative Pledge / Floating Charge |
| Mid-Market Corporate Exporters | 3-Month KIBOR (12.26%) | +1.75% to +2.75% | 13.78% - 14.78% | Mortgage on Factory Land & Plant Machinery |
| Commercial Trading Enterprises (SME) | 1-Month KIBOR (12.40%) | +2.75% to +4.00% | 14.50% - 15.75% | Hypothecation of Current Assets & Personal Guarantees |
| Unsecured Seasonal Agriculture Credit | 6-Month KIBOR (12.46%) | +3.50% to +5.00% | 15.95% - 17.45% | Agri Passbook / SBP Refinance Guarantee |