How the KIBOR Loan Calculator Works in Pakistan
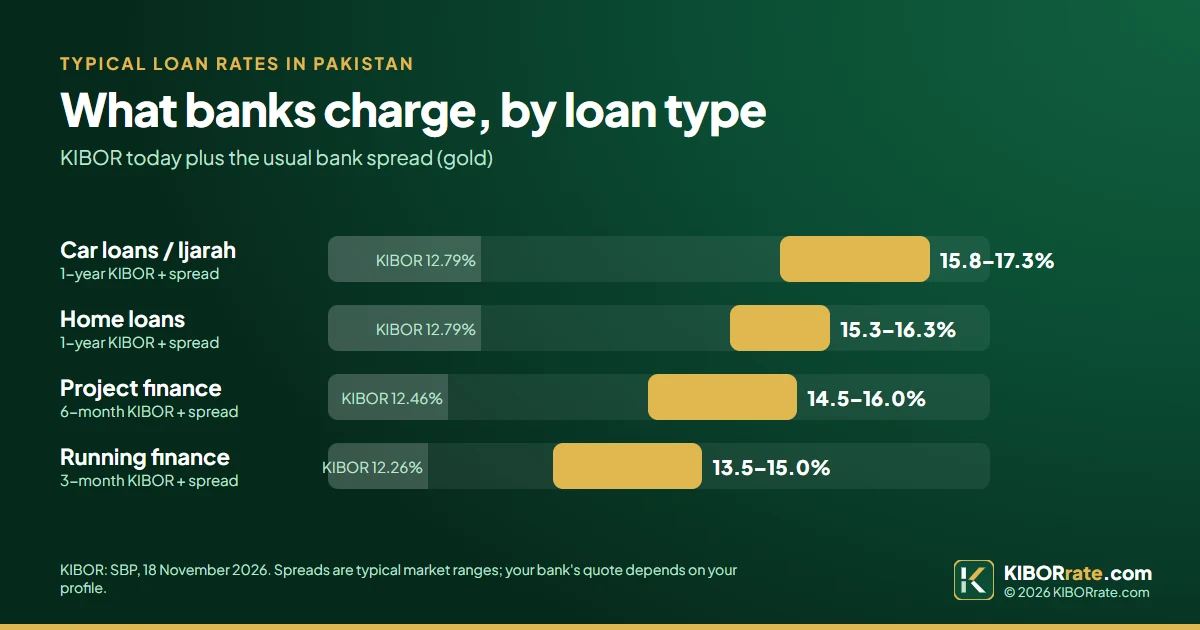
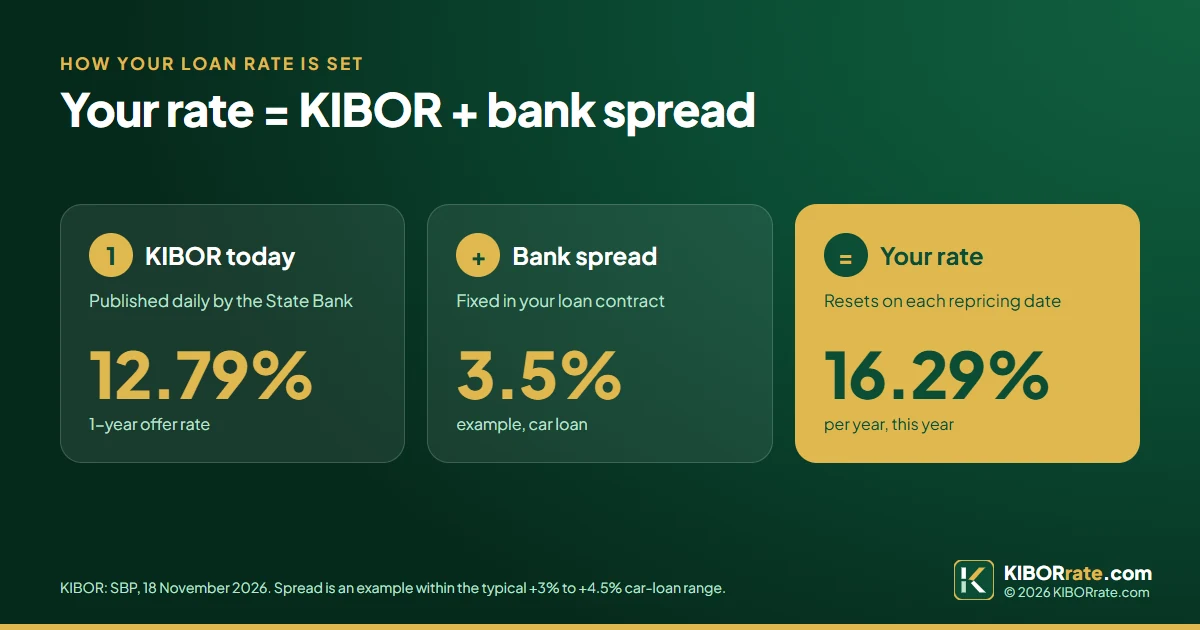
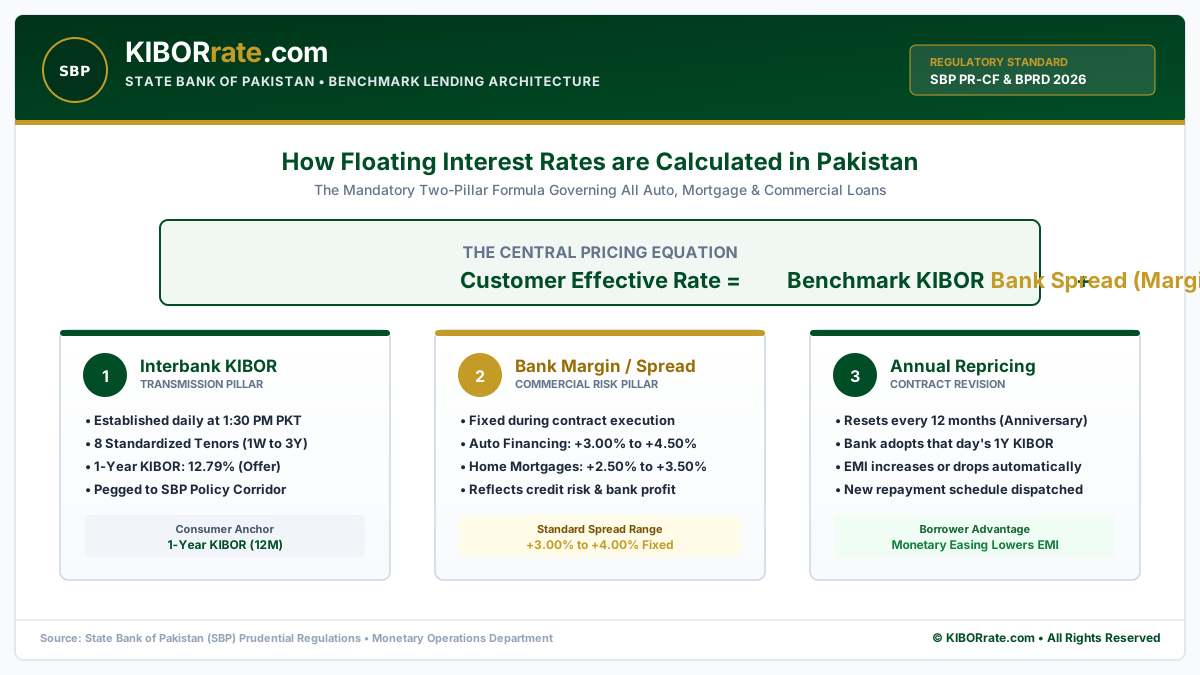
When applying for a commercial loan, personal finance facility, or equipment financing in Pakistan, commercial banks do not lend at a single fixed interest rate. Instead, State Bank of Pakistan (SBP) consumer guidelines require lending institutions to price loans based on a benchmark floating mechanism known as KIBOR plus a Spread.
The KIBOR Benchmark
KIBOR is the core cost of funds determined in the interbank market. For consumer and commercial loans, banks generally peg contracts to 1-Year (12-Month) KIBOR or 6-Month KIBOR.
The Bank's Spread (Margin)
The spread is the bank's profit margin and credit risk buffer. It typically ranges from +2.50% to +4.50% and remains constant throughout your loan tenure.
Equated Monthly Installment (EMI)
Using the reducing balance amortization formula, your monthly installment pays down both the accrued markup and the principal loan balance every single month.
Why Do You Need This Calculator?
Most commercial banks in Pakistan provide generic loan tables that assume fixed interest or fail to reflect the State Bank of Pakistan's latest rate adjustments. Using this calculator allows you to:
- Cross-verify Bank Quotations: Prevent loan officers from overcharging hidden spreads by seeing the true breakdown of KIBOR + Bank Margin.
- Plan Your Budget: Know exactly how much of your monthly income goes toward financing costs.
- Export Verified Cards: Share high-resolution quotation cards with your business partners, family members, or banking officers via WhatsApp.
What Happens During Annual Repricing?
On every 12-month anniversary of your loan, your bank will inspect that day's prevailing 1-Year KIBOR Offer rate. If the State Bank has cut monetary policy rates, your installment drops automatically for the next 12 months. If rates increase, your installment adjusts accordingly.
The Mathematics of Reducing Balance Loan Amortization
Pakistani commercial banks calculate Equated Monthly Installments (EMI) using the monthly compound reducing balance formula:
Where: P = Principal Financed
r = Monthly Interest Rate (Annual Rate ÷ 12 ÷ 100)
n = Total Tenor in Months
Because interest is calculated only on the remaining unpaid principal each month, the proportion of your installment that pays down actual principal increases with every passing month, while the markup share decreases steadily.
Bid vs Offer Rate Selection
Under SBP regulations, when a bank lends funds to a borrower, it must apply the Offer Rate (the lending quotation). The Bid Rate is used when banks accept deposits or borrow in the interbank market. The standard spread between Bid and Offer is 50 basis points (0.50%).
Day-Count Precision
Markup accrual on PKR commercial loans is computed on an Actual / 365 Days basis. Leap years may account for 366 days under specific bank facility agreements sanctioned by the State Bank of Pakistan.
Early Prepayment Penalties
SBP consumer rules cap early settlement charges on personal loans and auto financing, typically between 1.0% to 3.0% of the remaining outstanding principal if prepaid within the first 24 to 36 months.