Complete Guide to Home Financing & Diminishing Musharakah in Pakistan
Securing a housing loan (Mera Ghar / Home Value) in Pakistan is one of the most substantial financial commitments a family or property investor will ever undertake. Because mortgage terms stretch across 15, 20, or 25 years, minor differences in bank margins or shifts in KIBOR create massive financial swings.
How Diminishing Musharakah Operates
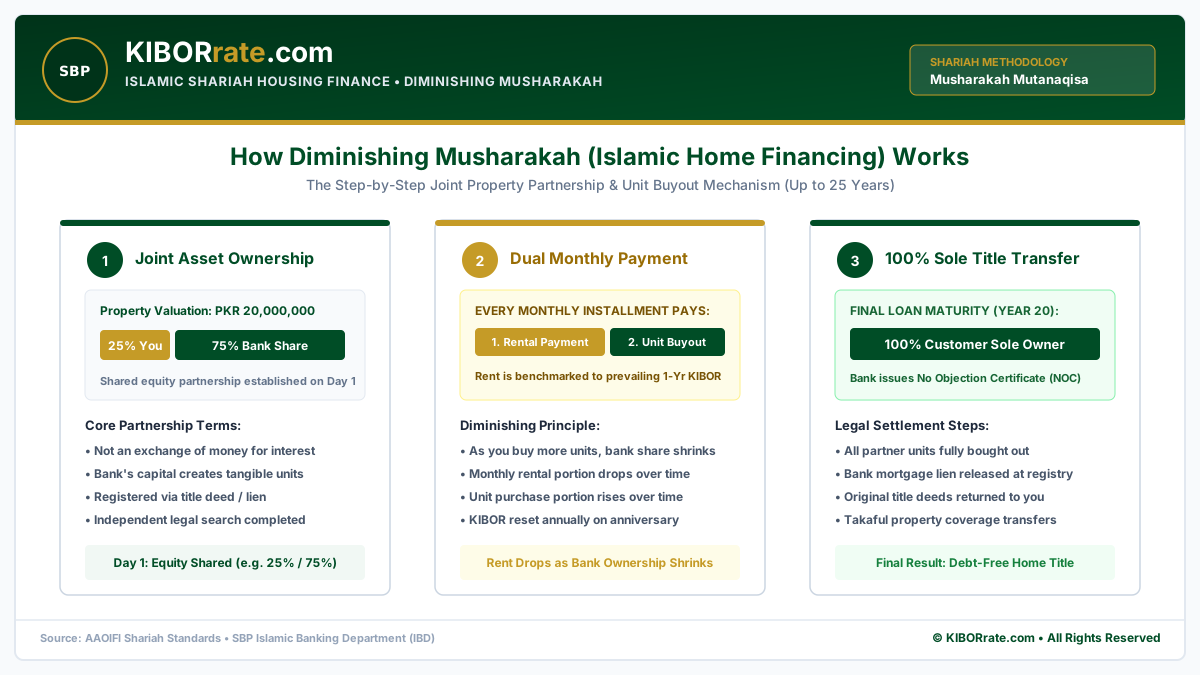
In Islamic banking (Meezan Bank, BankIslami, Faysal Bank), you and the bank enter into joint ownership of the property. The bank's share is divided into units. Each month, you pay rent for utilizing the bank's share and purchase one unit of bank ownership until you become the 100% sole owner.
Why KIBOR Matters Over 20 Years
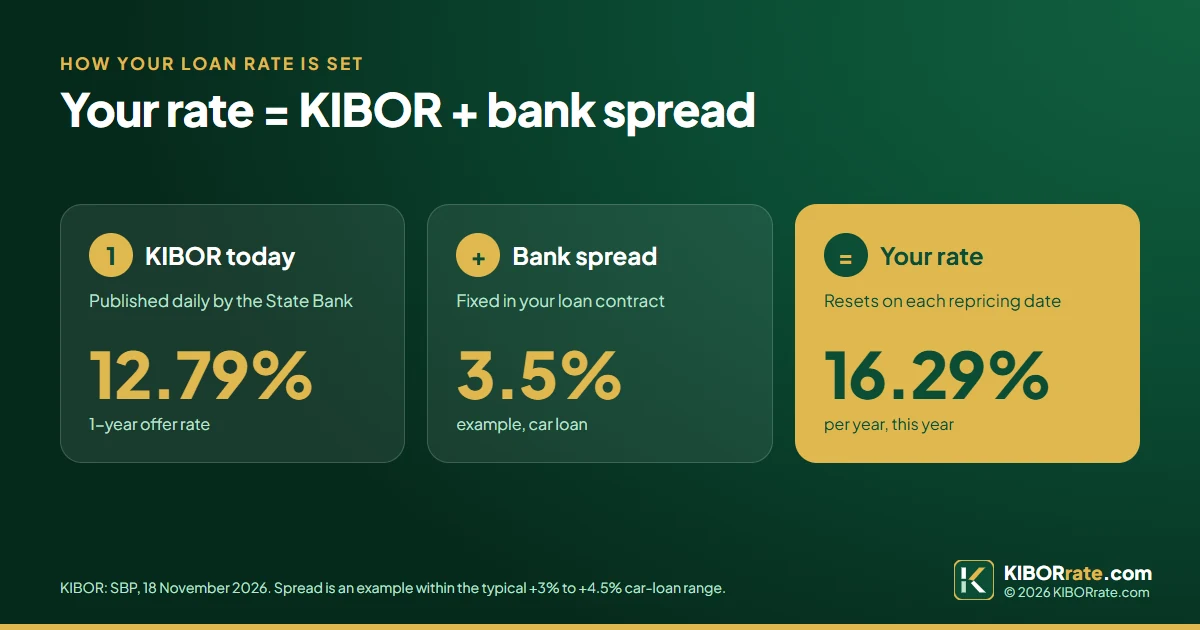
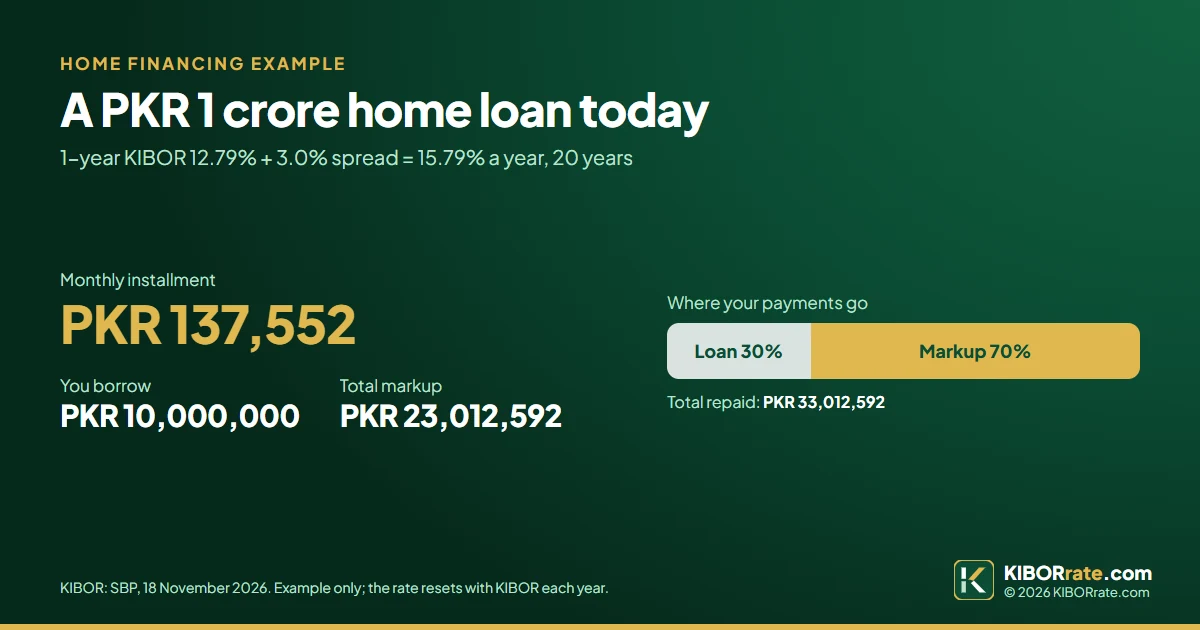
Home financing contracts reprice annually based on 1-Year KIBOR. If national inflation cools and SBP lowers interest rates, your monthly payment decreases automatically. If rates rise, your installment increases.
Property Valuation & Legal Verification
Before disbursing funds, Pakistani banks require approved legal counsel search reports, title deeds verification from the development authority (e.g. LDA, KDA, CDA), and independent valuation inspection.
Key Documents Required by Pakistani Banks for Housing Loans
- For Salaried Individuals: Last 12 months bank statements, salary slip certified by HR, employment proof, and CNIC copy.
- For Business Persons / Non-Salaried: 2 years verified bank statements, NTN certificate, FBR tax returns, and business registration.
- Property Documentation: Copy of Allotment Letter / Sale Deed, approved architectural map, and non-encumbrance certificate (NEC).
Shariah Legitimacy: Why KIBOR is Permissible in Diminishing Musharakah
A frequent objection raised by Pakistani home buyers is: "If Islamic banks peg their rental rates to KIBOR, how is it different from conventional interest?" Respected Shariah scholars (including Mufti Taqi Usmani and the SBP Islamic Banking Advisory Committee) have issued comprehensive rulings clarifying this standard:
Risk of Loss Sharing
Unlike a conventional mortgage where the borrower bears 100% of property destruction risks, under authentic Diminishing Musharakah, physical destruction of the property (force majeure) is co-shared proportionally according to equity ownership percentages.
Approved Development Authorities
Pakistani banks finance residential properties with clear titles registered under approved authorities including LDA (Lahore), KDA (Karachi), CDA (Islamabad), DHA, Bahria Town, and Cantonment Boards.
Mandatory Takaful Coverage
Banks mandate comprehensive Property Takaful (covering natural disasters, fire, and structural damage) and Mortgage Life Takaful (which pays off the remaining loan balance in the event of the primary earner's demise).
Comparison of Major Housing Finance Facilities in Pakistan
| Bank & Scheme | Contract Type | Benchmark Tenor | Typical Bank Margin | Max Tenor | Maximum Loan Size |
|---|---|---|---|---|---|
| Meezan Bank • Easy Home | Diminishing Musharakah | 1-Year KIBOR (12.79%) | +2.50% to +3.25% | 25 Years | Up to PKR 50 Million |
| Bank Alfalah • Islamic Home Finance | Musharakah Mutanaqisa | 1-Year KIBOR (12.79%) | +2.75% to +3.50% | 20 Years | Up to PKR 35 Million |
| Habib Bank Limited • HBL HomeValue | Conventional Mortgage | 1-Year KIBOR (12.79%) | +2.75% to +3.50% | 20 Years | Up to PKR 40 Million |
| Faysal Bank • Noor Home Finance | Shariah Compliant | 1-Year KIBOR (12.79%) | +2.50% to +3.25% | 20 Years | Up to PKR 50 Million |