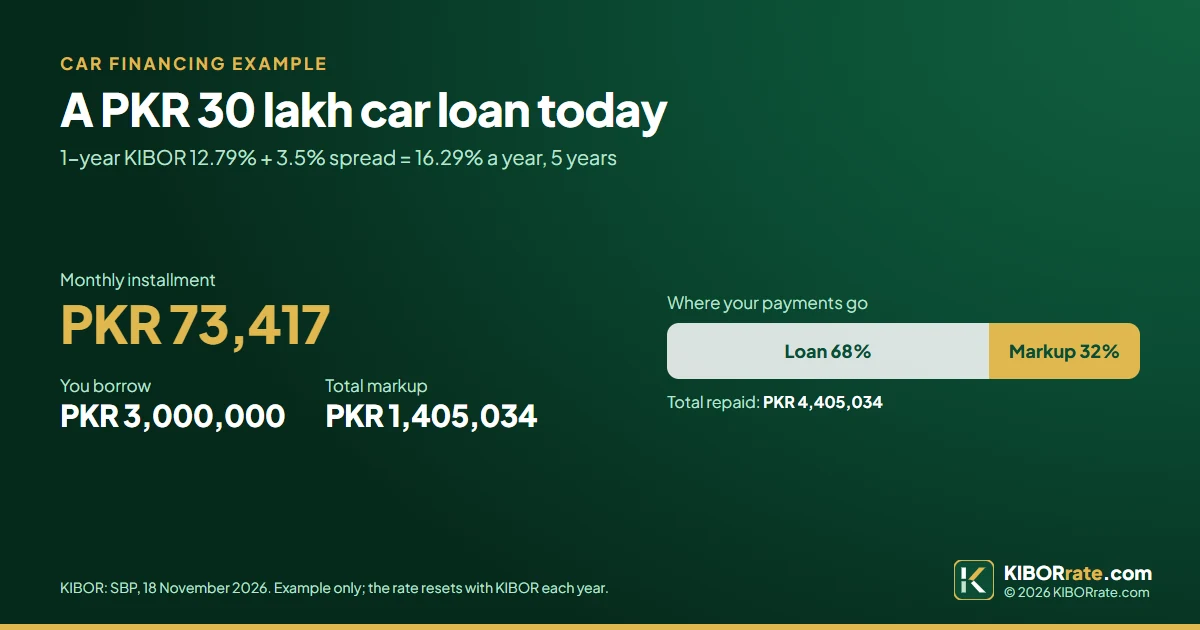
How Floating Rate Repricing Operates in Pakistan
When you sign a car loan, housing mortgage, or corporate facility in Pakistan, your sanction letter contains a clause called the Repricing Anniversary. Unlike fixed-rate economies, Pakistani banks reset your markup rate periodically (usually every 6 or 12 months) based on the latest published State Bank of Pakistan KIBOR rates.
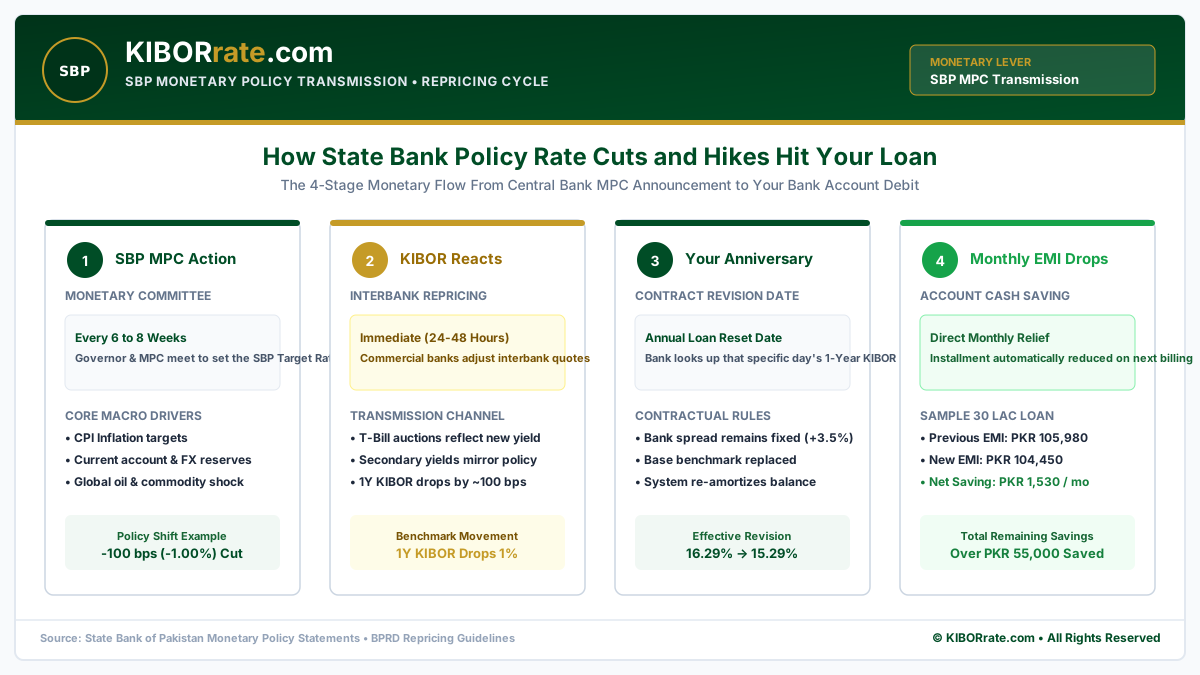
Monetary Policy Committee (MPC) Action
The State Bank of Pakistan meets roughly every 6 to 8 weeks to determine the national policy rate based on inflation, GDP growth, and foreign exchange reserves.
Interbank Transmission
As soon as SBP alters the policy rate, commercial banks adjust their daily bidding for treasury bills and interbank funds, which shifts KIBOR almost immediately.
Your Contract Reset Date
Your bank does not change your installment every day. Instead, it waits for your anniversary month, grabs that day's KIBOR Offer rate, re-calculates your EMI, and issues a new repayment schedule.
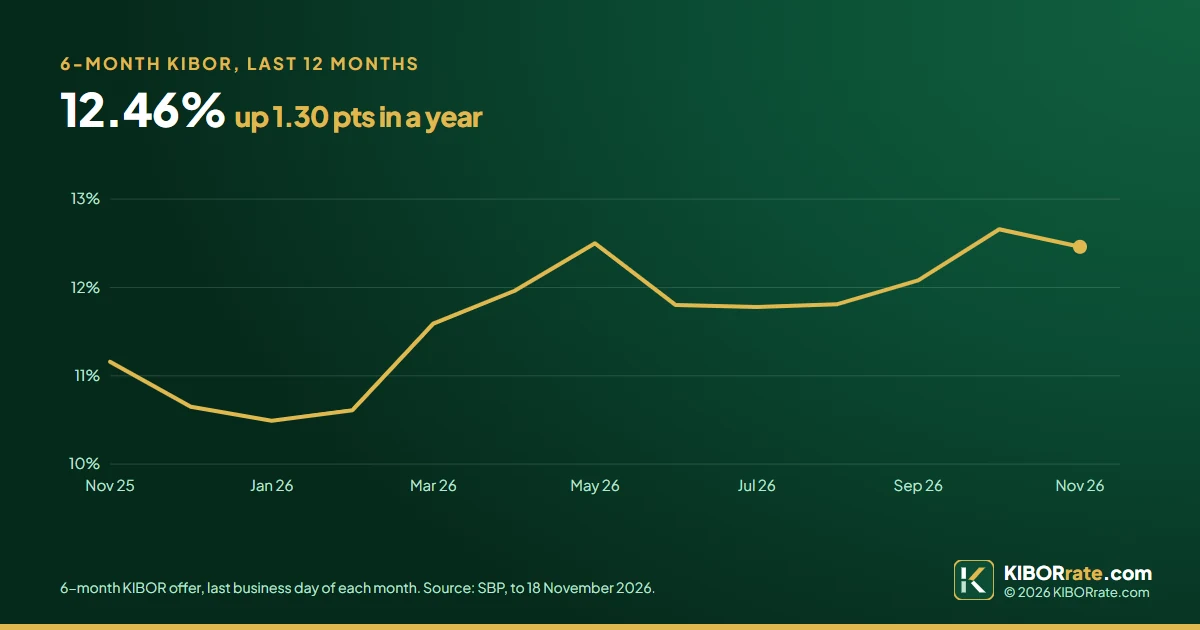
How to Strategize Ahead of Rate Changes
If financial analysts and the State Bank forecast monetary policy easing, prospective borrowers should request 1-Year floating KIBOR terms rather than fixed-rate products. Conversely, if inflation is surging, making partial prepayments (balloon payments) directly into your loan principal cushions against upcoming installment hikes.
The Economics of the Monetary Policy Transmission Mechanism
The transmission lag in Pakistan between a State Bank Monetary Policy decision and the actual revision of consumer loan installments typically spans 1 to 12 months depending on your contract anniversary. Understanding this calendar allows borrowers to accurately plan annual family and corporate budgets:
The SBP MPC Calendar
The Monetary Policy Committee (MPC) of the State Bank of Pakistan convenes roughly eight times a year. Meeting dates are published on the SBP website well in advance, accompanied by official Monetary Policy Statements (MPS) detailing inflation forecasts.
Sensitivity per 100 bps (1.00%)
For an average auto loan balance of PKR 3,000,000 over 3 years, every 100 basis point (1%) rate cut reduces the monthly installment by approximately PKR 1,530 / month, saving roughly PKR 55,000 over the term.
Balloon Prepayments
When interest rates are rising, making partial principal repayments (balloon prepayments) lowers your outstanding principal balance, thereby keeping your monthly installment manageable even after an upward KIBOR adjustment.
Historical SBP Monetary Policy Shifts vs. KIBOR Reactions
| Monetary Policy Epoch | SBP Policy Target Rate | 1-Year KIBOR Benchmark | Impact on Consumer Borrowers | Key Economic Trigger |
|---|---|---|---|---|
| June 2023 (Peak Tightening) | 22.00% | 23.20% - 23.45% | Highest monthly installments in Pakistani history | Surging headline CPI inflation (38%) |
| December 2024 (Aggressive Cuts) | 13.00% | 13.80% | Major monthly cash flow relief on repricing | Sharp drop in national inflation numbers |
| Late 2025 (Accommodative Low) | 10.50% | 11.15% - 11.25% | Lowest consumer auto/mortgage markups in 4 years | Macroeconomic stabilization & FX buildup |
| October 2026 (Stabilization) | 12.00% | 12.79% (Offer) | Equilibrium financing rate for commercial banking | Balanced growth & global energy trends |